Contents
§0 History
The calculus of variations may be said to have begun with Newton's problem of minimal resistance, proposed in 1687, followed by the brachistochrone problem proposed by Johann Bernoulli in 1696. The subject immediately attracted the attention of Jacob Bernoulli and Marquis de l'Hôpital, but it was Leonhard Euler who began to develop it systematically in 1733. Lagrange, influenced by Euler's work, made major contributions to the theory. After Euler saw the work published in 1755 by the nineteen-year-old Lagrange, he abandoned part of his own geometric approach in favor of Lagrange's purely analytic method and renamed the subject in his 1756 lectures Elementa Calculi Variationum.
Legendre proposed a method in 1786 for distinguishing maxima from minima, although it was not entirely satisfactory. Isaac Newton and Gottfried Leibniz had also given some early attention to the subject. Other contributors included Vincenzo Brunacci (1810), Carl Friedrich Gauss (1829), Siméon Poisson (1831), Mikhail Ostrogradsky (1834), and Carl Jacobi (1837). An important work by Sarrus (1842) was simplified and improved by Cauchy (1844). Other significant papers and treatises include those of Strauch (1849), Jellett (1850), Otto Hesse (1857), Alfred Clebsch (1858), and Lewis Buffett Carll (1885), but perhaps the most important work of the century was that of Weierstrass. His celebrated course on the theory was epoch-making, and he may be regarded as the first person to place the calculus of variations on a firm and indisputable foundation. Hilbert's 20th and 23rd problems, published in 1900, further stimulated the development of the subject.
In the twentieth century, David Hilbert, Oskar Bolza, Gilbert Ames Bliss, Emmy Noether, Leonida Tonelli, Henri Lebesgue, and Jacques Hadamard all made important contributions to the calculus of variations. Marston Morse applied variational methods to what is now known as Morse theory. Lev Pontryagin, Ralph Rockafellar, and F. H. Clarke developed new mathematical tools in optimal control theory. Richard Bellman's dynamic programming provides an alternative approach to the calculus of variations.
§1 Introduction: Stationary Values of Integrals
First, let us recall the basic principle from calculus for finding maxima and minima of functions of one variable:
Principle (a maximum is a stationary point). Let be a “good” function. Then a maximum or minimum of occurs where
Here “good” means continuously differentiable. In this article we will not carefully distinguish every possible exceptional case. We will usually assume that the functions under consideration are sufficiently smooth that differentiability causes no difficulty.
The calculus of variations is a collection of techniques in which, instead of looking for maxima or minima of a function of one variable, we look for extrema of a functional—a function of functions. That is, we choose a function so as to minimize some quantity. Problems of this kind occur frequently in physics.
Example 1 (Shortest Path Between Two Points) Given two points
in two-dimensional space, what is the shortest path between them?
By rotating the plane, which does not change the distance between the two points, we may assume
Let us imagine that the path is described by a suitable “good,” continuously differentiable function . Then the length of the path is
The only constraint on is
Since
we can see that the integral is minimized when
and hence the straight-line path minimizes the distance.
Intuitively, any path can be approximated arbitrarily well by smooth paths, so considering only smooth paths is sufficient. This is not the main point here, because throughout this article we will often assume, without rigorous justification, that we may restrict ourselves to sufficiently good functions.
Notice that we have derived a local rule about what happens at a point from a global criterion involving variations among all possible paths. This is the basic idea of the calculus of variations. We will generalize it considerably and apply it to a wide variety of problems.
One of the simplest ideas in physics is that light travels in straight lines. This idea becomes much more powerful when expressed as follows: light travels in straight lines because a straight-line segment is the shortest distance between two points. This may sound like a trivial restatement, but it remains one of the basic ideas underlying Einstein's general relativity and is closely connected with the modern quantum-electrodynamic understanding of light, so it should be taken seriously.
Example 2 (The Biathlon Problem) A group of athletes travel from point to point . They must first cross a field, running at speed , and then cross a river, swimming at speed . Which path from to takes the least time?
Clearly, the athlete should run in a straight line from to some point on the riverbank and then swim in a straight line from to , because straight lines minimize distance.
If , consider the final point at which the athlete is still in the field. The fastest way to get from to is to run along a straight line. After that, the fastest way to reach is to swim along a straight line.
Let
We want to choose so that the total time is minimized. At the optimal value of ,
Thus
Therefore the optimal position of is such that the angles satisfy
You may recognize (1) as Snell's law, which describes the refraction of light passing from one medium into another, provided that the refractive index of the medium is proportional to the inverse of the speed. Fermat observed that Snell's law follows from a principle of least time, although the principle was not understood from the perspective of quantum physics and relativity until the twentieth century.
We can now solve a slightly more general problem. Suppose someone runs through muddy terrain for , with speed proportional to , where is some smooth function depending only on the -coordinate. Equivalently, we have an optical medium whose continuously varying refractive index is proportional to . What path gives the shortest travel time between two points?
We can think about the problem as follows. Divide the muddy region into strips of thickness , so that in the strip from to , the speed is treated as the constant .
Repeatedly applying Snell's law (1), we obtain
Now take the limit
The same law remains valid.
§1.1 A Little Basic Calculus
The angle between the path and the -axis satisfies
We also have the definition of arc length
Putting these together,
From this we can also derive
where is the curvature of the path, defined in a way that is invariant under rotations of the coordinate axes.
Example 3 (Shortest Paths on a “Muddy Field”) As a particularly interesting example, take the case where is linear in . In fact, suppose
Then
Thus Snell's law can be reformulated as the statement that is a solution of
If , this gives the line
For , we obtain
That is, the solutions form a family of circles whose centers lie on .
This completely solves the problem of finding the shortest-time path for a runner between any two points in the region. We will return to this beautiful geometric fact later.
Clearly, we could now consider the more general problem in which
Instead, we will change our point of view and reformulate the problem in more general terms.
We regard the time required to traverse a path as a functional of that path. That is, it is a function on a space of possible paths, and the possible paths themselves are functions.
More specifically, in the problem we have been considering, define a functional on functions by
We then seek a minimum of as ranges over all possible paths. A function at which such a minimum is attained is called an extremal.
In this case, it is clear that we are looking for a minimum of the integral, but this is too restrictive in general. We therefore use the term stationary value. This will mean, in a sense still to be defined, that the first derivative of vanishes. This allows several possibilities: a minimum, a maximum, something analogous to a saddle point, or more complicated cases in which higher derivatives also vanish.
We now regard this as a special case of the more general problem of finding stationary values of the functional
Here
is a specified function.
For simplicity, we write
The remarkable discovery, due in principle to Euler and Lagrange, is that there is a single method for treating all such problems. The method can also be generalized further, to multiple dimensions, higher derivatives, and constraints.
Even more remarkably, problems that look nothing like least-time problems can be reformulated in this way. The trajectories of dynamical systems can be regarded as solutions of stationary-value problems—not problems of shortest distance or least time, but of least action, as we will explain.
This is an extremely useful description of physical problems, partly because the notion of a stationary value does not depend on the coordinates used to describe it.
Modern theoretical physics is rooted in the idea of stationary values of functionals of fields. The present Standard Model of particles and forces is defined by writing down a principle of least action, as are string and superstring theories.
Thus part of the motivation for the calculus of variations comes from the deepest properties of the physical world, properties revealed only through the transformative power of creative mathematics.
§2 Euler-Lagrange Equations
We now consider, in general, the problem of finding a function that gives a stationary value of the functional
When proving Picard's theorem in Differential Equations 1, we sometimes regarded as a function of three independent variables , and sometimes, after substituting
regarded it simply as a function of .
For example, the chain rule gives
Here
means the partial derivative of with respect to its third variable , evaluated at
From a completely rigorous point of view, we would need to specify the exact class of functions on which the functional is to have a stationary value: differentiable functions, functions with continuously differentiable derivatives, functions differentiable to all orders, and so on.
We would also need some notion of what it means to change a function to a “nearby” function, by putting a metric, or at least a topology, on the class of functions.
In this article we assume that all functions are sufficiently differentiable for the problem at hand.
We generally state results for smooth, infinitely differentiable functions, because most situations arising in the real world are smooth, or can be approximated arbitrarily well by smooth functions.
To justify this approach, we use bump functions.
Lemma 2.1 (Bump Function) There exists a function with the following properties:
(1) is infinitely differentiable;
(2) unless
(3)
if
Proof: Let
Then for every ,
as
because exponential decay dominates polynomial growth.
Thus is infinitely differentiable at and , and hence everywhere.
Clearly,
and
if and only if
By considering
we can define a bump function on any interval .
By rescaling, we may also assume that it takes the value at the midpoint, where it attains its maximum. This will sometimes be convenient.
Thus a function can always be varied inside any interval, by adding a bump function, without affecting its differentiability, and the precise degree of differentiability being discussed is not important.
Lemma 2.2 (Test Function Lemma I) Let be continuous on and suppose
for every smooth function satisfying
Then
for every
Proof: Suppose, for contradiction, that for some
Without loss of generality, suppose
Then there must be some interval containing , with
such that
throughout , since is continuous.
Now choose a bump function supported on .
By assumption,
Since
unless
this means
But this is impossible, because
is positive and continuous on this interval.
This contradiction shows that
on .
A small variation of this theorem is the following.
Lemma 2.3 (Test Function Lemma II) Let be continuous on , and let be constants such that, for every smooth function ,
Then
and
for all
Proof: Suppose first that
Without loss of generality, assume
Let be a bump function on
so that
for
and
For sufficiently small ,
This is a contradiction.
Therefore,
The same argument gives
Then Lemma 2.2 gives
as required.
We now begin the analysis of stationary values of the functional .
We might be tempted to try to vary using some infinitesimal function , but there are infinitely many possible functions, which would create many difficulties.
Instead, to avoid worrying about all these possibilities at once, we focus on a single one-dimensional family of variations.
Fix a function and consider
where is a real parameter.
This allows us to consider
In particular, we have the following lemma.
Lemma 2.4 (A Minimum Gives a Stationary Value) Let give a minimum of , and let be a smooth function. Then
Proof: This is really just another form of the standard minimum criterion from elementary calculus.
If gives a minimum of , then for all in a neighborhood of zero,
Thus
has a minimum at
Therefore
which is precisely the statement of the lemma.
Lemma 2.5 (A Constrained Minimum Gives a Stationary Value) Let give a minimum of subject to
and let be a smooth function satisfying
Then
Proof: The proof is the same as before. Observe that if
then
still satisfies
Theorem 2.6 (Euler-Lagrange Equation with Natural Boundary Conditions) Let
for some smooth function .
Then a minimizing function satisfies
and
Proof: Let
minimize , and let
be a smooth function.
By Lemma 2.4,
Applying the chain rule,
Here, by
we mean
where
The next key step is integration by parts, which removes .
First observe that
Hence
Here
denotes the total derivative, acting on every explicit or implicit appearance of , including those through and .
Therefore,
For to be an extremal, the left-hand side must vanish for every choice of .
Hence the right-hand side must vanish for every .
By Lemma 2.3, this implies
and
as required.
Theorem 2.7 (Euler-Lagrange Equation with Fixed Endpoint Boundary Conditions) Let
for some smooth function .
If minimizes subject to
then
Proof: The proof is essentially the same as before.
By Lemma 2.5, we consider only functions satisfying
For all such functions,
The term
vanishes because
By Lemma 2.2,
as required.
Note that finding an extremal or stationary value is not the same thing as finding a maximum or minimum.
Additional information is needed to determine whether an extremal is a local maximum, a local minimum, or neither.
However, maxima and minima must be extremals.
§3 Classical Examples and Basic Theorems
We now return to the first two examples from the point of view of the Euler-Lagrange equation.
Example 4 (Shortest Distance in the Euclidean Plane) Minimizing the distance of a path between
is equivalent to minimizing
subject to
where
Since
the Euler-Lagrange equation becomes
Since
is constant, is constant, and therefore the solution is a straight line.
Example 5 (Shortest Path on the “Muddy Field”) Next, we verify that the paths in the muddy-field problem of §1 are circles.
We take
The Euler-Lagrange equation is
Integrating,
This is the same equation as (4), which we derived from the generalized Snell's law.
To remind you, the solutions are circles whose centers lie on the -axis.
Again, one should also consider both fixed-point and natural boundary conditions. You can check that these make the solutions meaningful.
§3.1 An “Ignorable Coordinate”
You should pay particular attention to the way these problems reduce from second-order ODEs to first-order ODEs.
The reason is that the particular function
does not depend explicitly on :
This is extremely important, especially in applications to mathematical physics.
In this situation, the dependent variable is called ignorable.
We can state a general theorem.
Theorem 3.1 (A Special Case of the Euler-Lagrange Equation) Let
be a smooth function such that
Let be a minimizer of the functional
Then
is constant.
§3.2 The Same Problem from Another Reference Point
Suppose instead that we consider stationary values of the functional with
The geometric interpretation immediately tells us that the extremals must be circles whose centers lie on the -axis.
However, this is not obvious from the Euler-Lagrange equation
which appears to be a complicated second-order ODE.
The key is to notice that when does not depend explicitly on , a more general result is available: Beltrami's identity.
This is also extremely important.
Theorem 3.2 (Bletrami's Identity) Let
be a smooth function such that
Let be an extremal of
Then
That is,
Proof: Since
we have
By the Euler-Lagrange equation, this is
This proves the result.
Alternative proof:
Although the preceding proof is easy, it does not explain why this first integral exists.
The following argument explains the reason: it is really just a special case of an ignorable coordinate.
We simply interchange the roles of and and regard the curve as a function
rather than
In the particular problem under consideration, this is obviously a very natural idea.
Write
so that
The integral
becomes
Now is an ignorable coordinate, so the Euler-Lagrange equation becomes
Taking the partial derivative carefully, remembering how expressions such as
are properly defined, gives
Here
Therefore,
which is equivalent to Beltrami's identity.
Applied to the muddy-field problem, we obtain
The remaining integration can then be carried out directly, yielding circular paths.
In this case, there is no solution satisfying the natural boundary conditions.
This agrees with the fact that the integral has neither a minimum nor a maximum between and .
It can take any positive value, and its infimum is never attained.
We will return to this shortest-path problem, or more generally the problem of geodesics, in Lecture 5.
It turns out that the “muddy field” is actually a way of representing the central mathematical structure of the hyperbolic plane.
Example 6 (The Brachistochrone Problem) Find a curve along which a particle released from rest at some point reaches a given lower point, not directly beneath the starting point, in the shortest possible time.
We assume gravity is a constant force .
This is one of the most famous stationary-integral problems solved by Newton, J. Bernoulli, and others in the seventeenth century.
The answer is not intuitive.
Some first-year mechanics is needed to obtain the relevant function
In this problem, we use for horizontal distance and for vertically downward distance.
This convention is chosen simply so that the motion can begin at the origin without introducing expressions such as
Suppose the particle is released at
from
and then moves along the curve
which reaches
where is the vertical drop and the horizontal distance.
Using the initial conditions and conservation of energy, at every point on the curve,
Hence
where
Therefore,
Thus the total time is a functional of the curve :
We seek a curve minimizing subject to fixed endpoint conditions through
Notice that this may also be interpreted as a muddy-field problem in which the speed is proportional to
We could easily derive the Euler-Lagrange equation, but it is more efficient to use Beltrami's identity, since
depends only on and .
This gives
for some constant .
To solve this equation, make the substitution
Then
Thus, using the initial conditions,
This is a cycloid.
See the figures below:
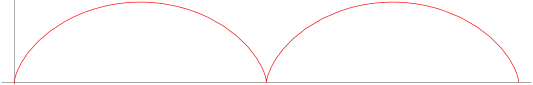
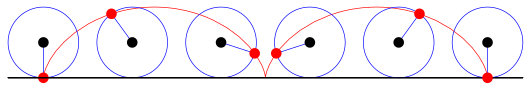
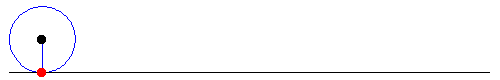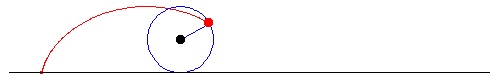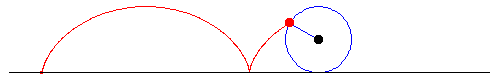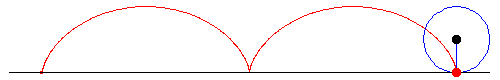
The ratio determines the portion of the cycloid that solves the problem.
If
then the cycloid extends all the way to its lowest point
where
If
then the solution is a smaller segment of a cycloid, with chosen appropriately, and so on.
A few further details are worth adding.
One finds that
is constant, namely
Thus the time required to reach the point with parameter is
Suppose the horizontal distance is given, and we seek the path that reaches this horizontal distance most quickly among all possible .
The time is
where is determined implicitly by
Thus finding the fastest way to reach is equivalent to minimizing
It can be checked that this is minimized at
This verifies the result
at
obtained from the natural boundary condition.
It selects the cycloid that reaches its lowest point at , namely
Example 7 (Soap Film) Consider the surface obtained by rotating the curve
about the -axis between
Which curve gives the minimum area?
The objective in this problem is to minimize an area, but because the surface is a surface of revolution, the problem reduces to finding a curve.
You can imagine this as a soap film suspended between two circular wire loops at
with the assumption that the film reaches equilibrium at the position of minimum area.
The functional to be minimized is
The integrand has no explicit dependence on , so Beltrami's identity gives a first integral:
Its solution is
Filling in the details and fitting the initial conditions is a somewhat tedious process and is left as an exercise.
The hyperbolic cosine curve appears again in another problem: finding the shape of a freely hanging chain.
Because of this connection, it is called a catenary.
The surface we have found is a catenoid, which plays an important role in the geometry of surfaces.
Example 8 (A Typical Second-Order Ordinary Differential Equation Problem) Suppose
Then
and the Euler-Lagrange equation is
In this case, there is no ignorable coordinate or Beltrami identity to help us.
However, we recognize this second-order ODE as a type studied extensively in differential-equations courses, with boundary conditions that can be handled using a Green function.
We will not investigate the solution of this equation further here.
Instead, we are more interested in the reverse question:
can differential equations that we have encountered previously be reformulated as problems of finding extremals?
§4 Extension to Several Variables and Hamilton's Principle
In this section, we explore applications of the calculus of variations to classical mechanics.
First, we need a modest generalization to allow several dependent variables.
It is convenient to change notation, because in mechanical applications time is usually the single independent variable, while the dependent variables represent the spatial coordinates of the mechanical system.
Thus, instead of and
we first consider
and
where is a typical spatial coordinate and is time.
There is a reason for using rather than for the dependent variable.
We do not want to restrict ourselves to Cartesian coordinates, and the letter might misleadingly suggest that we are doing so.
The variable could be an angle, a radial distance, or something else.
We then generalize to
and
Thus we consider stationary values of the functional
Theorem 4.1 Let be a smooth function and define
Then minimizing functions
satisfy
together with the natural boundary conditions
Subject to the constraints
the minimizing functions of satisfy equation (37) above, but need not satisfy equation (38).
Sketch of proof:
The method for finding these minimizing functions is the same as in the simplest case.
Choose an index and a test function , temporarily fix for
and vary only :
Since all with
are temporarily fixed, the functional has exactly the form already considered.
The Euler-Lagrange equation gives
and the natural boundary condition is
Repeating this procedure for each index gives the result.
There are two important special cases:
- If some variable does not appear in , then it is an ignorable coordinate:
- If is independent of time , then there is a generalized form of Beltrami's identity:
§4.1 Hamilton's Principle
The following statement summarizes why classical mechanics can be reformulated as an extremal problem and solved using the calculus of variations.
Definition 1. If there is no friction in a mechanical system and a constraint does no work, the constraint is called a workless constraint.
If a constraint has the form
where the are coordinates and the constraint does not involve the velocities , then the constraint is called a holonomic constraint.
If a force is the gradient of a potential function , it is called a conservative force.
Principle (Hamilton's Principle). If a mechanical system is subject only to holonomic workless constraints and all forces are conservative, then according to Newton's laws the motion of the system is an extremal of the integral
where the coordinates are arbitrary but unconstrained and
that is, the kinetic energy of the system minus the potential energy, expressed in these coordinates.
is called the Lagrangian.
This is Hamilton's principle, also known as the principle of least action, and the integral
is called the action.
In this article, we take this as known without proof, meaning that it correctly encodes the physical laws.
In a classical-mechanics course, one proves that it is equivalent to Newton's laws.
Notice that the dimension of is energy multiplied by time.
“Action” is the name given to a physical quantity with these dimensions.
It turns out to be one of the most fundamental physical quantities; in particular, Planck's constant is a quantum of action.
Example 9 (Motion in Free Space with No External Forces) The simplest example is
The Euler-Lagrange equations are
which are Newton's equations of motion for a free particle.
Example 10 (Motion in Free Space under a Conservative Force) The next simplest example is
describing motion in free space under a conservative force with potential , typically Newtonian gravity.
The Euler-Lagrange equations become
The value of the stationary-integral formulation often becomes more obvious after changing coordinates.
For orbital problems with
Cartesian coordinates work, but are not especially useful.
Since the form of the Lagrangian does not care which coordinates we use, spherical polar coordinates are more convenient.
Example 11 (Orbital Problem with Potential ) In polar coordinates
for motion in free space with potential
we have
The equation is
One solution is
meaning that the path remains in the equatorial plane.
Restricting attention to such paths, the remaining equations become
The same equations are derived by a longer argument in elementary dynamics.
Clearly, the equation integrates to
It is extremely important to notice that the simplicity of this step follows directly from the fact that never appears in .
It is an ignorable coordinate.
Conservation of angular momentum is therefore a direct consequence of an ignorable coordinate in the Lagrangian formulation of Hamilton's principle.
Conservation of energy can be derived just as easily.
It corresponds to Beltrami's identity.
Since has no explicit dependence on ,
is constant along the trajectory.
From the original form of , before restricting to equatorial trajectories, it is immediately clear that in this case
the total energy.
For an equatorial orbit this reduces to
Thus the entire problem is reduced to a single integration, yielding the familiar conic-section solutions.
The two simplification theorems we have used—ignorable coordinates and Beltrami's identity—point toward a profound feature of physical theories.
There is a direct relationship between symmetry, meaning invariance under a family of transformations, and conservation laws.
Independence of the angle means that the action is invariant under
and this is equivalent to conservation of angular momentum.
When is ignorable, so that the action is invariant under
the momentum in the -direction is conserved.
When
is a symmetry, energy is conserved.
Notice that
angle angular momentum,
length momentum,
and time energy
all have the dimensions of action.
These conjugate relationships become crucial in quantum mechanics and form the basis of the famous Heisenberg uncertainty principle.
The Euler-Lagrange equations must retain the same form under coordinate transformations because the notion of stationarity does not depend on which coordinate system is used to describe the problem.
Technically, this means that we can write and in whatever coordinates we like, without having to carry out complicated chain-rule transformations of the equations.
We illustrate this simplicity with several examples.
§5 Further Examples in Physics and Geometry
So far, we have not made use of the new freedom provided by imposing holonomic constraints.
A typical problem studied in elementary dynamics is that of a particle moving smoothly on a surface of revolution, such as the paraboloid
Let us derive the equations of motion from Hamilton's principle.
Example 12 (Motion on a Paraboloid) At any instant, the position of the particle may be written as
In other words, we have used the holonomic constraint supplied by the smooth surface to eliminate one of the three spatial dimensions, reducing the problem to two dimensions.
Here we use
as the two required generalized coordinates , although in principle we could use any coordinates we like.
It is a good idea to choose the angle as one of the two coordinates because then it becomes ignorable in , producing a simple first integral.
Specifically,
The fact that is ignorable implies
for some constant .
Since has no explicit dependence on and is quadratic in the velocities, it follows that
is conserved.
Thus all the results of the elementary treatment can be obtained immediately, without eliminating reaction forces by taking dot and cross products with vectors.
Example 13 (Particle on a Rotating Wire) A particle moves smoothly along a straight wire inclined at an angle to the vertical, while the wire rotates about the vertical axis with constant angular velocity .
In elementary dynamics, starting directly from Newton's second law requires eliminating the normal reaction force by taking the dot product of Newton's second law with a vector tangent to the wire.
Using Hamilton's principle, we may ignore the normal reaction force and work directly with the Lagrangian
Relative to an inertial frame, the particle position is
The mass of the particle is irrelevant, so we may set it equal to .
The kinetic and potential energies are
There is only one generalized coordinate, , and therefore only one Euler-Lagrange equation.
It immediately gives the equation of motion
This is exactly the equation required by the problem.
One must also ask whether
is conserved.
In fact it is not.
A torque must be applied to keep the wire rotating at constant angular velocity , and therefore work must be done.
The Lagrange method does better.
It constructs a conserved Hamiltonian , but this Hamiltonian is not equal to the total energy:
The Hamiltonian differs from because is not a homogeneous quadratic polynomial in the velocity.
The kinetic energy contains both a contribution involving and one involving .
We are now free to consider more general problems that would be difficult to solve using elementary dynamical methods.
Example 14 (Motion on a General Surface with No External Forces) Suppose a particle moves on a fairly general surface embedded in three-dimensional space.
In the discussion that follows, we assume that the particle always remains in contact with the surface and do not worry about how this can be physically enforced.
You can imagine a spacecraft whose outer surface consists of two layers, with the particle moving between them so that the normal reaction force can point either inward or outward.
Hamilton's principle immediately provides a Lagrangian for the motion: it is simply the kinetic energy constrained to the surface.
Suppose the surface is parametrized by
so that a point is given by
Writing in the coordinates gives
where
We may now write the Euler-Lagrange equations and in principle determine the entire motion.
In general, the resulting second-order differential equations for and are not easy to solve.
The simplifying feature is that the path followed by the particle is a geodesic on the surface—a stationary value of arc length.
To prove this, first observe that a purely “kinetic-energy” Lagrangian, one quadratic in the velocities and with no explicit dependence on , has a special property.
By Beltrami's identity, the value of itself is constant along the motion.
The kinetic energy is also positive definite.
Suppose is some strictly increasing function on the positive real numbers, and consider the stationary-value problem for .
The Euler-Lagrange equations are
Since
and
this reduces to the Euler-Lagrange equation for .
Taking
shows that
produces the same Euler-Lagrange equations.
But this is exactly the arc length of the trajectory on the surface, and arc length is stationary along geodesics.
If desired, we may eliminate the time variable and write the integral as
where
is regarded as defining a curve on the surface.
This is exactly of the form studied earlier.
Thus, in the absence of external forces, a particle simply follows the shortest path compatible with the geometric constraint, at least in the sense of a local minimum.
In this case, least action coincides with shortest distance.
This is a generalization of Newton's second law.
§5.1 More Geodesics
Example 15 (Cylinder) Suppose the surface is the cylinder of radius whose axis is the -axis.
Its parametrization is
We compute
so
The Lagrangian is simply the kinetic energy:
Thus the geodesics satisfy
These are straight lines in the coordinate system.
The same conclusion can also be obtained by finding geodesics as curves of stationary arc length.
The method above gives
so the geodesics have the form
Notice that paths on a cylinder clearly illustrate the difference between a local minimum of path length and a global minimum.
Why is the problem so simple?
The key is that although a cylinder is regarded as a surface in , it is intrinsically flat.
This is intuitively clear: the surface can be unrolled without stretching and laid flat on the Euclidean plane.
The correct terminology is that it is isometric to the plane.
Under such an isometry, geodesics are preserved because they are intrinsically defined.
It is worth noting that the concept of a geodesic is much more general than the case of surfaces discussed here.
We do not need to restrict ourselves to surfaces embedded in three-dimensional space.
The metric can be given abstractly; in fact, we did something similar with the “speed” function in the opening lecture.
Nor must we study geodesics only on surfaces.
We can equally well study geodesics in spaces of arbitrary dimension.
In physics, this idea played an extremely important role in the development of Einstein's general relativity.
In general relativity, gravity becomes part of the geometry of four-dimensional spacetime rather than being a force, and trajectories of freely falling bodies, including light rays, must be geodesics in the resulting space.
The four-dimensional space is not regarded as something embedded inside a larger space.
In pure mathematics, the study of geodesics is an important part of geometry and can be pursued further in a course on the Geometry of Surfaces.
§6 Generalization to Several Independent Variables and Higher-Order Derivatives
§6.1 Several Independent Variables
Suppose that instead of considering stationary values of functionals of curves
we move up one dimension and consider variations of a surface
Define the functional
where is some region in the -plane and
are the partial derivatives of with respect to and .
For example,
gives the area of a surface and therefore allows the study of minimal surfaces in great generality, not just surfaces of revolution.
As usual, the method is to vary the dependent variable along a one-dimensional path:
This gives
We can use the divergence theorem, or Green's theorem since we are in two dimensions, to eliminate and :
Here
is the outward-pointing normal vector on the boundary curve , and is arc length.
Under fixed boundary conditions,
on .
Therefore the boundary integral vanishes, giving
We conclude that the Euler-Lagrange equation must hold at every point in :
This generalizes immediately to independent variables rather than two.
The result is the following theorem.
Theorem 6.1 Let be smooth and let
be a functional over a region
on smooth functions
where
Then a minimizing function satisfying fixed boundary conditions on satisfies the Euler-Lagrange equation
Note that in the theorem above, we assume not only that is sufficiently “good,” but also that the region is sufficiently well behaved for the conclusion to hold.
Introducing the notation
allows us to write the Euler-Lagrange equation more compactly as
Example 16 (Variational Formulation of Laplace's Equation) A simple and beautiful example is obtained by taking
Then the Euler-Lagrange equation is
Thus we obtain Laplace's equation, or its -dimensional generalization.
This shows that problems involving Laplace's equation or the wave equation can be reformulated naturally in variational form.
This idea is fundamental both in modern quantum field theory and in the numerical solution of elliptic equations by finite-element methods.
§6.2 Higher-Order Derivatives
Now suppose we wish to find stationary values of the functional
Varying as before gives
Integrating by parts twice gives
Thus a necessary condition for a stationary solution is the Euler-Lagrange equation
This is a fourth-order differential equation and requires four constants of integration.
These constants must be obtained from suitable endpoint conditions, now involving both and , together with the natural boundary conditions
Example 17 (Diving-Board Problem) We study a problem illustrating how the calculus of variations can solve practical optimization problems arising in engineering and economics.
Consider the functional
This functional may be interpreted as the total energy of an elastic beam of horizontal length .
The beam is clamped at
so at that point
while it is free at
and bends under its own weight.
We assume is sufficiently small that this functional gives a reasonable approximation to the physical situation.
The beam will reach an equilibrium position minimizing its energy, so the calculus of variations provides a method for determining its shape.
The Euler-Lagrange equation is
Two of the four boundary conditions are
and the other two are the natural boundary conditions
This clearly specifies a quartic polynomial.
The solution satisfying the boundary conditions is
Notice that the free end of the diving board sags to
Imagine a swimmer in a pool placing a hand on the free end and holding it at the height
Clearly, if
no force need be applied.
But if
a force is required.
We can evaluate this force by extending the analysis.
First solve the stationary problem again with the fixed-end condition
To simplify notation, write
It is easy to find
We can now regard the energy functional as a function of .
It has a minimum when
If the free end is lifted, the energy increases, and this increase can only come from work done.
The work is
where is the force required to maintain
Therefore,
This is easily calculated to be
Returning to the case where the end at is free, we may apply the same idea to find the force applied at
to maintain the constraint.
In this case, it is easier to see that the upward force required to maintain
is simply the total weight of the diving board,
Slightly less obvious is the fact that the clamp applies a torque of
to maintain the condition
Here we use
You may already be familiar with the idea of forces associated with constraints, because this is exactly the idea behind normal reaction forces in elementary mechanics.
But suppose the functional measures not energy, but cost.
Then each element of the problem, including the constraints, acquires an economic interpretation.
You can imagine the diving-board curve as describing the effect of a company acquiring a hospital and replacing a stable-employment policy with a policy of reducing staff.
Here the independent variable is time and represents staff size.
How should the policy be implemented at minimum cost?
Suppose the cost functional contains the same kinds of terms as the diving-board functional:
wages proportional to , and costs associated with management disruption, strikes, and so on caused by rapid changes in staffing, modeled as proportional to
The solution with natural boundary conditions represents the ideal situation at the end of the period, from the company's perspective rather than that of the patients.
If a government regulator imposes a constraint specifying the staff level that must remain at that time, then the constraint naturally acquires a price:
the amount the company would be willing to pay to persuade the regulator to reduce the imposed quota by one unit.
In optimization courses, through linear programming, you have already encountered the idea that prices arise as dual variables associated with constraints.
This is another example of the same idea.
§7 Extremals with Integral Constraints
This section studies how to find stationary values of an integral
subject to the integral constraint
We can solve this problem using the method of Lagrange multipliers from elementary calculus.
Suppose and are two linearly independent test functions and consider the variation
where and are real parameters.
For fixed and , this defines two functions of and :
From elementary calculus, we know that the problem of finding stationary values of
subject to
is equivalent to finding stationary values of
Since this is true for every pair of linearly independent , and indeed for variations of the form
with real parameters and linearly independent test functions , it is reasonable to conclude that stationary values of under the constraint
can be found by looking for stationary values of
Thus must satisfy the Euler-Lagrange equation
for some constant .
In addition, must satisfy the appropriate fixed-endpoint or natural boundary conditions.
The natural boundary condition is now
We record this result as a useful theorem.
Theorem 7.1 Let be smooth functions, and define
Then every smooth stationary value of subject to
satisfies
for some constant .
A Freely Hanging Chain—the Catenary
We can use this method to determine the shape of an idealized chain of constant density supported only at its two ends.
Suppose the chain lies along the curve
with endpoints fixed at
Its total length is fixed:
where
The equilibrium state of the chain minimizes its gravitational potential energy:
Applying the method of Lagrange multipliers and absorbing into , we obtain
This has no explicit dependence on , so Beltrami's identity gives the first integral
Substituting
easily yields the solution
Matching the constants
to the given data
is left as an exercise.
Dido's Problem
Another similar classical problem is the simplest isoperimetric problem.
In the Euclidean plane, given a fixed length as perimeter, what is the largest possible enclosed area?
The answer is a circle.
We consider a slightly different version in which the area lies on one side of a given straight line, which we may take without loss of generality to be the -axis.
The answer is then that the boundary is a circular arc.
This problem is known as Dido's problem, because it can be regarded as appearing in the Aeneid.
Dido, perhaps more widely known through the famous lament she inspired in Purcell, is said to have fixed the boundary of Carthage according to this criterion.
The line
represents the Mediterranean coastline.
For more information, see http://mathworld.wolfram.com/DidosProblem.html.
For this problem, we may take
and
where the boundary curve is represented as
However, it is actually better to represent the boundary curve parametrically as
where is an arbitrary parameter.
We consider extremals of the functional
The Euler-Lagrange equations are
Therefore,
Eliminating gives
Integrating,
Thus the curves must be circles.
For the original Dido problem, we are interested in the fixed boundary condition
at both endpoints, together with the natural boundary condition for .
That is, with fixed, we consider extremals over all possible values of .
The natural boundary condition for is
Since
this implies
Here
is infinite, which explains why the representation is inappropriate.
Thus the center of the circle must lie on
and under the given constraint the stationary area is bounded by a semicircle, as expected.
These are the same semicircles that appeared as the fastest paths in the muddy-field problem, or more formally, as geodesics of the hyperbolic plane.
This can be seen more directly by proceeding in a slightly different way.
The second equation in (47) may be written
so
Imposing the boundary conditions
forces this constant to be zero.
Hence
This is the same equation that appeared in the fastest-path problem, in (28), and therefore has the same semicircular solutions.
This feature extends to a more general land-enclosure problem in which a varying value
is associated with the land, and the objective is to maximize total value for a given boundary length.
In this case, the problem can be represented by taking
where
With natural boundary conditions, the resulting equation is
You can check that this is the same equation obtained in the muddy-field fastest-path problem when the speed of motion is
Thus, if
then
and we recover the equation arising in the brachistochrone problem in (30).
Hence the solution is a cycloid.
Constraints and Prices Revisited
We now have another example in which a constraint can be regarded as defining a price.
If we change the constraint
to
how much additional can be obtained?
Let
denote the stationary value of under the constraint
Then we find
This gives a useful interpretation of .
To prove it, recall that the solution of
is stationary.
That is, when the extremal is changed to any
consistent with the boundary conditions, the value is unchanged to first order.
Suppose we choose a particular such that
is the extremal for the problem with constraint
Then, to first order,
Subtracting and taking
recovers the relation.
Thus, in Dido's problem, the value of in the solution represents the value of the additional area obtained by increasing the available rope length defining the perimeter.
We have therefore solved an additional question:
how much should Dido be willing to pay for additional rope?
More specifically, in this problem, for perimeter length the stationary area is
Therefore,
which is exactly the radius of the circle.
It is easy to check that this is indeed the value of .
§8 Application to Sturm-Liouville Equations
§8.1 Motivation from Quantum Mechanics
In quantum mechanics, the state of a physical system is not described by the motion of point particles, but by wavefunctions.
These wavefunctions are actually complex-valued, but for simplicity we may discuss real functions.
The simplest case is a single particle confined to a finite one-dimensional interval
Although a classical point particle could simply remain at rest in this interval with zero kinetic energy, a wavefunction is associated with the integral of the square of its derivative, essentially half the kinetic energy:
So far this looks somewhat like the kinetic energy of a fluid, but there is a subtle difference that makes wavefunctions completely different from classical fluids.
The energy is actually determined by the ratio
Thus multiplying by a constant has no effect.
The energy is a functional of the shape of , not its overall scale.
In particular,
has no meaning in this ratio, so there is no obvious analogue of a stationary classical particle.
Instead, a minimization problem appears, but its answer is far from intuitively obvious.
In fact, among functions satisfying
the minimum is
We will prove this.
The existence of such a nonzero ground-state energy is characteristic of quantum systems in much more general settings.
We need a formalism that can handle this problem and more general ones in which the energy functional is more complicated and the geometry of space is not simply an interval.
Clearly, the theory of stationary integrals with integral constraints provides exactly such a framework.
The ratio above can be reformulated as the problem of minimizing
subject to
Thus the ratio of interest can be related to the value of the Lagrange multiplier in the solution.
From the preceding discussion, the relationship between and in this example is particularly simple: it is linear,
and can be interpreted as a constant price.
The new point here is that, for the first time, we seriously consider the existence of many local extrema—indeed, a countably infinite number—and study their relationships.
The relationship between these extrema is naturally expressed by observing that is also an eigenvalue of a differential operator.
§8.2 Sturm-Liouville Equations
The differential operator of interest is the same one you may have encountered in Differential Equations 2, but written in a slightly different form.
The standard Sturm-Liouville form is
where
are continuously differentiable, and we assume
This is the Euler-Lagrange equation for the variational problem of finding stationary values of
We can now identify boundary conditions consistent with this interpretation.
At each endpoint we may usually choose either a fixed boundary condition or a natural boundary condition.
Thus at we have either
or
and similarly at .
§8.3 Examples
- If
we recover the example from the beginning of this section.
Now we can solve it.
The allowed values of are
and the corresponding are proportional to
- If
we obtain Legendre's equation on
With natural boundary conditions, the solutions are the Legendre polynomials
as encountered in Differential Equations 2.
- If
we obtain
Equivalently,
This may also be recognized from Differential Equations 2 as Bessel's equation of order .
When
the solution vanishing at
has the form
A more complete treatment would introduce solutions of Bessel's equation that diverge at
In the simplest case, when the boundary condition
is imposed at
and
there is a discrete spectrum
such that
vanishes at both
and
§8.4 Eigenfunction Expansions
The idea of Sturm-Liouville theory is to generalize the Fourier analysis naturally associated with the first example.
You may have encountered Sturm-Liouville theory in Differential Equations 2.
The time-independent Schrödinger equation in Quantum Theory, on a bounded domain, is a special case of a Sturm-Liouville problem with taken to be constant.
From elementary Fourier series and partial differential equations, you know how completeness and orthogonality allow general functions to be expanded in sine and cosine functions.
It turns out that these properties are not restricted to trigonometric functions.
Sines and cosines may be viewed as solutions of a Sturm-Liouville ordinary differential equation, and any other Sturm-Liouville equation generates a new family of functions with analogous completeness and orthogonality properties.
That is, for a general Sturm-Liouville equation there is usually a sequence of eigenfunctions
with completeness and orthogonality properties, so that general functions can usefully be expanded as
just as in Differential Equations 2.
A complete statement and proof lie beyond the scope of this course.
Remember that even in Fourier theory, completeness is subtle and requires special care at discontinuities.
However, we can show how the important orthogonality property follows directly from the present formulation.
Suppose that for a Sturm-Liouville system
we have two solutions
corresponding to
First, we verify that the eigenvalue associated with the eigenfunction is equal to the quotient
and hence equals the Lagrange multiplier in the integral formulation.
We have
Multiplying by and integrating,
Therefore,
That is,
But at the boundary , we have either
or
and similarly at .
Therefore the boundary term vanishes.
Hence, as required,
We now prove that
are orthogonal, meaning
We have
Multiply the first equation by , the second by , subtract, and integrate from to :
The left-hand side integrates exactly to
This vanishes because of the boundary conditions.
At , either
or
and similarly at .
Thus the right-hand side vanishes.
Since
orthogonality follows.
This argument is the same as the one used in algebra courses when discussing the general definition of an inner product.
In fact, we have defined an inner-product structure on a function space using
as a weight function.
We can then choose the normalization so that
thereby obtaining an orthonormal family of basis functions with respect to this inner product.
§8.5 The Rayleigh-Ritz Approximation Method
Throughout the course, we have emphasized that the variational formulation works in both directions.
Our theory solves famous extremal problems by solving differential equations.
Conversely, it can effectively reformulate problems involving differential equations as problems of stationary integrals.
In the context of Sturm-Liouville equations, spectral eigenvalues can be studied effectively by computing the integrals
and
In particular, any trial function satisfying the boundary conditions gives an upper bound for the lowest eigenvalue
Returning to the original example,
we may try the simplest function satisfying the boundary conditions:
Then
Hence
This is a good approximation to
The procedure can be improved.
Clearly, optimizing the trial function over a family containing several parameters can improve the approximation.
In this way we obtain a good approximation
to
The next eigenvalue can then be estimated by optimizing over the class of all trial functions orthogonal to
This gives an approximation to
and
and so on.
The reason eigenvalues are approximated especially well is that if the trial function
is correct to
then the eigenvalue
will be correct to
Indeed, if
where every
is
then the difference between
and
is
because